Car Insurance Edmonton
Car Insurance Edmonton: Compare Auto Insurance Quotes with a Licensed Broker
Car insurance in Edmonton starts with three coverages every Alberta vehicle must carry, and Sharp Insurance’s licensed brokers shop that coverage with several insurers at once so you get a choice of quotes from one conversation (IBC). We arrange auto insurance for Edmonton drivers by phone, online and through our app.
Two things make this a good time to review your policy. Alberta’s Care-First system replaces most injury lawsuits with guaranteed benefits on January 1, 2027, and the rules for capping renewal increases change on the same day (alberta.ca).
Get an Edmonton car insurance quote or call toll-free 1-877-218-2008
How to Get an Edmonton Car Insurance Quote in 2026
There are several different ways to get a car insurance quotes in Edmonton:


| Sharp Insurance for Edmonton drivers | |
| How we serve Edmonton | By phone, online quote and the mySHARP app; documents by email |
| Phone | Toll-free 1-877-218-2008 · 403-590-2008 |
| Head office | 1331 Macleod Trail SE #300, Calgary, AB T2G 0K3 (no Edmonton walk-in office) |
| Hours | Monday to Friday, 8:30 a.m. to 5 p.m. |
| Insurers we work with | Economical (Definity), Intact, SGI Canada, Wawanesa and Aviva |
| Licensing | Licensed through the Alberta Insurance Council; member of the Insurance Brokers Association of Alberta |
| In business since | 2009 · Part of Synex since 2021 |
Usually, the easiest and fastest way to get a quote in 2026 is online. The more information you have written down ahead of time, the more accurate your quote will be.
What car insurance do Edmonton drivers need?
Every vehicle on Edmonton roads must carry third-party liability of at least $200,000, accident benefits and direct compensation for property damage (DCPD). Collision and comprehensive are optional under Alberta law, though a lender or leasing company will usually insist on both (alberta.ca).
|
Coverage
|
Mandatory?
|
What it does for you
|
|
Third-party liability |
Yes, at least $200,000 |
Pays others when you injure someone or damage their property, plus your legal defence |
|
Accident benefits |
Yes |
Pays your own medical, rehabilitation and lost income after a crash, no matter who caused it |
|
DCPD |
Yes (since January 1, 2022) |
Your own insurer repairs your car when someone else is at fault (alberta.ca) |
|
Collision |
No |
Repairs your car when you cause a crash or hit an object, such as a pole in a parkade |
|
Comprehensive |
No |
Theft, hail, fire, flood and vandalism |
| Endorsements | No |
Rental car, family protection, waiver of depreciation on a new vehicle |
Edmonton had an estimated 1,238,300 residents in 2025 (City of Edmonton), and many commute on the Anthony Henday, Whitemud Drive and Yellowhead Trail. Higher-speed ring-road collisions are where the $200,000 minimum can fall short. If you are found at fault for a serious injury, any award above your limit is your responsibility, which is why most brokers suggest $1 million or $2 million.
Myth: Your car insurance covers your laptop or tools if they are stolen from the car. Fact: Auto policies cover the vehicle; personal property inside it is usually a home or tenant insurance claim.
Your decision: what liability limit protects your savings, and whether you still need collision on the car you drive today.
Consider a 50-year-old in Terwillegar who drives a 2018 pickup to work, tows a camper to Jasper twice a summer and has a son at the University of Alberta who borrows the truck. A Sharp broker would check the liability limit, confirm the trailer is covered while towing and make sure the occasional driver is listed so a claim isn’t refused.
Honest limit: the insurer’s policy wording decides what is covered, not a summary on a web page. We send your full declarations and answer questions before you buy.
How much is car insurance in Edmonton?
Alberta drivers paid an average of $1,903 for car insurance in 2025, 8.7% more than in 2024, according to the province’s Automobile Insurance Rate Board (IBC, Aug 31, 2026). No official Edmonton-only average exists, so treat any city figure you see online as an estimate.
Comparison sites publish Edmonton averages from about $1,900 to $2,300 a year, each based on its own quote data and a sample driver profile, sometimes years old. The most useful number for you is a current quote on your own vehicle and record.
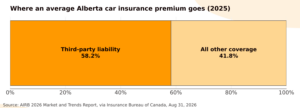
Source: AIRB 2026 Market and Trends Report, via IBC.
Takeaway: most of an Alberta premium pays for injury and liability claims against drivers, not for repairing their own cars.
|
What insurers look at |
How it affects an Edmonton premium |
|
Postal code |
Claims history in your area; theft and collision rates differ across the city |
|
Commute |
Daily kilometres, and whether you drive the Henday or Whitemud at rush hour |
| Vehicle |
Repair costs, theft appeal and safety technology |
| Driving record |
At-fault claims and convictions over recent years |
|
Drivers on the policy |
Young or newly licensed drivers in the household |
| Coverage choices |
Liability limit, deductibles and endorsements |
|
Other policies |
Bundling home or condo insurance with the same insurer |
Myth: Your premium is mostly about your car’s value. Fact: More than half of the average Alberta premium goes to third-party liability, so your driving record and coverage limits often move the price more than the car does.
Your decision: whether to compare insurers now or wait until your renewal notice arrives.
A couple in Mill Woods with two cars and a 17-year-old about to finish driver training should price the policy with and without the new driver before renewal. A Sharp broker can show both scenarios side by side across several insurers.
Honest limit: with a recent at-fault claim or a licence suspension, the lowest prices you see advertised won’t apply to you. We will still show every option available.
Edmonton auto insurance after January 1, 2027
From January 1, 2027, Edmonton drivers will be insured under Care-First, Alberta’s new system that pays injury benefits through your own insurer and limits lawsuits to cases where the at-fault driver is convicted of serious offences such as impaired or dangerous driving (alberta.ca). The legislation, Bill 47, passed in May 2025 (IBC).
|
If you are injured |
Until December 31, 2026 |
From January 1, 2027 |
|
Common injuries (sprains, strains) |
About 10 to 21 treatment visits | Treatment while it gives a measurable benefit |
| Serious injuries | Treatment capped at $50,000 |
No set maximum or time limit |
|
Lost income |
About $600 a week, up to 2 years | Up to $125,000 a year, to retirement if needed |
| Suing the other driver | Allowed |
Only after a conviction for certain Criminal Code offences |
|
High-risk driver grid |
In place |
Repealed (Canadian Underwriter) |
Source: alberta.ca, Care-First auto insurance, September 2026.
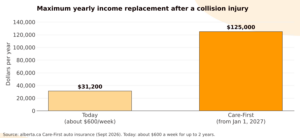
Source: alberta.ca. Today’s figure is $600 a week for 52 weeks.
Takeaway: a higher earner hurt in a collision in 2027 keeps far more of their income than one hurt today.
The province expects basic coverage to cost about $366 less per vehicle (CTV News, May 2026), and insurers’ approved Care-First rates cut private passenger premiums by 13.7% on average, about $297 per vehicle (Insurance Business, Sept 2026).
Did you know?
If you renew before Care-First starts, Alberta’s rate board has told insurers to waive the cancellation penalty when you switch to a Care-First policy later (Insurance Business).
Explore more:
How to Save Money on Car Insurance
Get a Quote
Myth: Care-First makes everyone’s premium drop by the same amount. Fact: The 13.7% is an average; your change depends on your insurer, vehicle, record and the coverage you choose.
Your decision: whether to keep your current renewal date or switch to a Care-First policy in January, and whether extra optional benefits are worth buying.
For a self-employed contractor in Windermere whose income swings each year, the new income replacement limits matter as much as the price. A Sharp broker can quote both your renewal and a January Care-First policy so you compare them in dollars.
Honest limit: the rate board has not yet published its 2027 rate guidelines, so nobody can guarantee every 2027 price today. We quote what insurers have filed and tell you when that changes.
Edmonton auto insurance rate caps at renewal
Edmonton auto insurance renewals in 2026 are capped at a 7.5% rate increase for good drivers, and from 2027 insurers’ average increase is limited to 5%, with no single driver’s renewal rising more than 10% (alberta.ca). Good-driver status requires meeting the province’s rules, including no minor traffic convictions in the past three years.
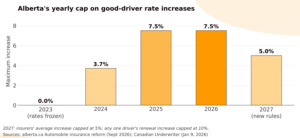
Sources: alberta.ca; Canadian Underwriter, Jan 9, 2026.
Takeaway: the allowed increase for good drivers has roughly doubled since 2024, so loyalty alone no longer keeps a renewal cheap.
In September 2026 the rate board stopped accepting new rate filings that would raise overall premiums until it issues 2027 guidelines (Insurance Business). Earlier, it pushed back on insurers that restricted collision and comprehensive coverage for drivers with claims or convictions (Insurance Business).
Myth: A capped renewal is always the best price available. Fact: The cap limits your current insurer’s increase; another insurer may still charge less for the same coverage.
Your decision: accept the capped renewal, or have a broker test it against other insurers before the due date.
For a retired couple in Belgravia on a pension, a few hundred dollars matters. A Sharp broker compares the renewal against other insurers and explains whether an increase comes from the rate or from a change such as a new vehicle.
Honest limit: if you have recent traffic convictions, the good-driver cap may not apply, and some insurers may offer only higher deductibles.
Theft, winter and storms: Edmonton car insurance risks
Vehicle theft is the Edmonton risk most drivers underestimate, and only comprehensive coverage pays if your car is stolen. Edmonton police recorded 4,233 stolen vehicles in 2025, down from 4,814 in 2024, and recovered 1,466 of them (Edmonton Police Service, Feb 2026).
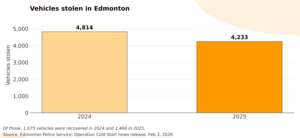
Source: Edmonton Police Service, Operation Cold Start release, Feb 3, 2026.
Takeaway: theft fell 12%, but more than 11 vehicles a day are still stolen in Edmonton, and most are never recovered.
Did you know?
Edmonton police run Operation Cold Start every winter to target thefts of vehicles left idling to warm up, often with the keys inside (EPS
Get a Quote
Storms add to the bill. Severe weather caused more than $330 million in insured damage across Alberta in 2023, including over $100 million to vehicles (IBC), and Edmonton-area storms between May and June 2026 caused about $230 million in insured damage, mostly to homes (Insurance Business, July 2026).
Myth: Warming up your car for a few minutes in your own driveway is safe. Fact: Edmonton police warn against leaving a running car unattended anywhere; take the keys, lock it, or use a remote starter.
Your decision: whether comprehensive is still worth it on an older car, and what deductible you could pay after a theft or storm.
If you park on the street in Oliver or Garneau, comprehensive and an approved immobilizer may matter more than collision. Our article on what happens if your car is stolen explains the claim steps.
Honest limit: insurance pays for the loss, but it can’t shorten the wait for a replacement vehicle or parts after a busy storm season.
Do tickets and photo radar affect car insurance in Edmonton?
Tickets for moving violations that carry demerit points can raise your Edmonton car insurance, but camera tickets are issued to the vehicle’s registered owner and the City says they carry no demerit points (City of Edmonton). Because they are not recorded as driving convictions against your licence, insurers generally don’t rate on them.
Since April 1, 2025, Alberta has banned photo radar on provincial highways and connector routes and limited speed cameras to school, playground and construction zones, with intersection cameras catching red-light running only (alberta.ca). Edmonton issued 34,351 red-light camera tickets in 2025 (City of Edmonton
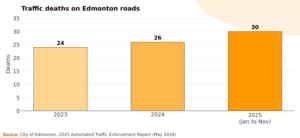
Source: City of Edmonton, 2025 Automated Traffic Enforcement Report, May 2026.
Takeaway: fatal collisions in Edmonton have risen each year since 2023, which feeds the injury costs behind everyone’s premium.
Police-issued tickets are different. A distracted driving conviction costs $390 and 3 demerit points (alberta.ca), and insurers check your driving record when you buy or renew.
Myth: Any ticket raises your insurance. Fact: Camera tickets with no demerits don’t count as driving convictions; tickets written by a police officer for moving violations usually do.
Your decision: whether to pay a police-issued ticket or dispute it, knowing a conviction may follow you at renewal for several years.
For a sales rep who drives across Edmonton all day, one distracted driving conviction can cost more in premiums than the fine. Before you renew, a Sharp broker can explain how a conviction on your record is likely to be treated by different insurers.
Honest limit: we can’t give legal advice on fighting a ticket. For that, speak with a traffic lawyer or paralegal.
How to get cheap car insurance in Edmonton
Cheap car insurance in Edmonton comes from comparing insurers, choosing deductibles you can afford and collecting every discount, not from cutting coverage you may need later.
- Shop at every renewal, especially for renewals near January 2027 when Care-First pricing applies.
- Bundle your car with Edmonton home insurance or condo insurance.
- Set your deductibles at a level you could pay from savings next week.
- Ask about discounts: winter tires, anti-theft devices, multiple vehicles, retirees, low annual kilometres and a clean record.
- Protect your driving record; police-issued convictions can affect your premium for years.
- Drop collision on a low-value car only after working out what replacing it would cost you.
Myth: The cheapest auto insurance in Edmonton is always online-only. Fact: Each insurer prices differently, so the cheapest option depends on your profile, not on how the company sells.
Your decision: which savings you’ll take this year, and which protection you won’t trade for a lower price.
For a nurse in Summerside who now works from home three days a week, lower annual kilometres can earn a discount that is easy to miss. A Sharp broker asks the questions that uncover it.
Honest limit: if a serious conviction is on your record, discounts won’t offset the surcharge; the goal is staying insured until it ages off.
Vehicle insurance in Edmonton for new, high-risk and specialty drivers
Sharp Insurance arranges vehicle insurance in Edmonton for drivers who need more than a standard policy, from newly licensed teens to riders, RV owners and drivers with a conviction. Each type has its own page.
High-risk drivers face the biggest change in 2027, because the grid that limited their basic premiums is repealed on January 1. If you rely on grid pricing today, ask for a quote before your renewal rather than after.
Myth: No one will insure you after a DUI. Fact: Alberta insurers must offer mandatory coverage to eligible licensed drivers; the price and optional coverage are what change.
Your decision: accept a higher premium now while you rebuild your record, or risk a gap in coverage that makes the next policy cost more.
For a parent in Castle Downs adding a newly licensed teen, or a retiree storing an RV over winter, a Sharp broker matches the risk with insurers that want it.
Honest limit: we can’t remove convictions or claims from your record, and some specialty coverage costs more wherever you buy it.
Why choose a Sharp car insurance broker for Edmonton?
A car insurance broker for Edmonton works on your side rather than for one insurer, so Sharp can compare several companies’ prices and coverage in one call and help if a claim stalls. We serve Edmonton drivers by phone, online and app from our Calgary office.
The best car insurance in Edmonton pays fairly when you claim, at a price you can keep paying, and a licensed adviser makes that easier to judge than a price list. Our team of Edmonton insurance brokers also handles home, condo and business insurance.
Get a QuoteMyth: A broker’s commission makes the policy cost more. Fact: The insurer pays the commission out of the premium; it is not an extra fee on your bill.
Your decision: handle renewals and claims yourself, or have a licensed broker do it with you.
If you’d rather not spend a lunch hour on hold with three insurers, one call to Sharp covers it. Our brokers are licensed through the Alberta Insurance Council.
Honest limit: we don’t have a walk-in office in Edmonton, and we don’t represent every insurer in Alberta. If face-to-face service in Edmonton matters most to you, a local office may suit you better.
How do car insurance claims work in Edmonton?
To claim on your Edmonton car insurance, report the loss to your insurer as soon as it is safe, using the claims line for your insurer, and contact Sharp if you need help. When another driver is at fault, DCPD means your own insurer handles the repair.
- Check that everyone is safe, and call 911 if anyone is hurt.
- Exchange names, licence and plate numbers and insurer details; photograph the scene and damage.
- Report the collision to police if anyone is injured or Alberta’s reporting rules require it.
- Call your insurer using the insurer claims numbers on our site, or start a claim with photos in the mySHARP app.
- Call Sharp if the claim stalls, the settlement looks low or you’re unsure what’s covered.
Myth: Asking your broker a question about a possible claim counts against you. Fact: A question isn’t a claim; premiums change based on paid claims and fault.
Your decision: whether to claim a small loss or pay it yourself to protect your claims history.
After a fender-bender on the Henday during a snowstorm, you want one app with your pink card and step-by-step help. mySHARP puts both on your phone.
Honest limit: the insurer decides whether a claim is paid and how much. We advocate for you, but we don’t control the outcome.
Explore more:
What affects the cost of auto insurance in Edmonton?
Premiums in Edmonton are heavily influenced by factors such as postal code, driving record, and annual mileage. For example, postal codes such as T5A, T5B, T5C, T5E, T5G, and T5H tend to have some of the highest average insurance premiums in the city. In contrast, areas such as T6J and T6T often have some of the lowest average insurance premiums in Edmonton. Also, insurance companies consider local crime rates, since areas with higher theft or vandalism rates may have higher premiums. 10 factors that affect car insurance rate in Edmonton:

- Your insurance history: Your driving history is a significant factor in determining car insurance rates, with insurers rewarding long-time drivers who are conviction and claims-free with lower rates.
- Your claims history: Drivers who have made several claims may pay higher premiums, since insurers see them as more likely to file more claims in the future.
- Your driving status: Insurers calculate premiums based on several factors, such as having a suspended or a restricted licence. Also, whether you’re a new driver or an experienced driver.
- Where you live: Insurance companies use postal code regions to price auto insurance, as some areas have higher rates due to a greater likelihood of claims such as theft and collisions.
- Age, marital status: Your age affects car insurance rates, with younger drivers in Edmonton typically paying higher premiums due to being statistically more likely to be involved in accidents.
- If you commute or use your car for work: Using your car for commuting or work usually increases your insurance rate because it means you spend more time on the road.
- The distance you drive each year: Your mileage impacts your insurance rates, as longer commutes increase the likelihood of being involved in an accident.
- If there is another driver on your policy: Adding another driver to your policy can affect your premium, especially if the driver is young or has a history of tickets or accidents.
- The make, model and year of your car: Some vehicles cost more to insure because they are more expensive to repair, easier to steal, or have higher accident rates.
- The MSRP or purchase price of your car: More expensive vehicles usually cost more to insure because repairs, parts, and replacements are more costly.
How Auto Insurance Pricing Is Regulated in Edmonton
Many drivers are surprised to learn that auto insurance pricing in Edmonton isn’t left entirely to insurance companies. The Alberta government plays an active role in overseeing how rates are set.
This oversight happens through the Alberta Insurance Rate Board (AIRB).
Before an insurance company can increase or change its auto insurance rates in Alberta, it must submit a formal application to the AIRB. The insurer is required to justify the change using claims data, loss trends, and financial projections. The AIRB reviews the request to ensure pricing remains fair and actuarially sound.
Readmore:
How do tickets impact Edmonton auto insurance in 2026?
Your driving record goes into account when calculating the factors affect car insurance premiums. Tickets can impact your Edmonton car insurance quotes significantly. In some cases, you may even see your coverage and payment options reduced and get cheaper car insurance. Insurance companies generally categorize tickets into three categories: minor, major, and serious traffic violations.

A minor traffic violation can spike your Edmonton car insurance rates by 25 percent per ticket. Many insurance companies forgive the first infraction, but often tickets will stay on your record for 3 years and impact your rates.
Minor Traffic Tickets
- Speeding 1 – 49km/h + over the limit
- Following too close
- Improper passing
- Improper turn
- Hogging the roadway

Serious traffic violations have consequences: your Edmonton car insurance prices can rise significantly, and you’re more likely to have issues when you pursue optional car insurance coverage or you want a convenient payment schedule.
Major Traffic Tickets
- Speeding 50km/h + over the limit
- Dangerous driving
- Racing
- Stunting
- DUI or distracted driving
What do you need to get an auto insurance quote in Edmonton?
It’s wise to have your personal information at your fingertips before you contact your insurer to call to get an insurance quote in Edmonton:
- Name
- Contact information
- Address
- Make, model and year of your vehicle (or VIN)
- Purchase price of the car
- Registration
- Driver’s license number
- Birthdate
- Current insurance company, policy number and coverages
If your car is financed, you’ll also need to provide information about the loan and lender. You’ll need the above information for each car and insured driver.

You’ll also likely be asked the following questions when getting an auto insurance quote in Edmonton:
- Do you commute with your car? If so, how far?
- Do you use your car for work (other than commuting)?
- Are you a ride-sharing driver?
- Was your vehicle bought new or used?
- Is your car financed?
- Does your vehicle have any existing damage?
- Have you been in any accidents in the last six years?
- Have you have had any claims?
- Have you gotten any tickets in the last three years?
Finally, you’ll need to make some decisions about your insurance coverage. This includes what protection you want, your policy limits (the maximum amount that you’ll get if you have a claim) and your deductible (the amount you pay out of pocket if you have a claim).
Get a Quote
Did you know?
- If you’re a new driver, you’ll pay a significantly higher auto insurance premium than if you have 10+ years of driving under your belt.
- You may be excused on your first ticket infraction, depending on your insurance company’s discounts. Ask your broker or insurer to see if you qualify.
Why do I need to provide so much information for a car insurance quotes in Edmonton?
The more information you provide for an auto insurance quote, the more accurate your quote will be. Insurance companies price based on risk — or how likely it is that you’ll have a claim or accident.
How do car insurance claims work in Edmonton?
Whether you’ve been in an accident, your car is damaged, or it’s been stolen, follow these steps for filing a car insurance claim in Edmonton:
- Make sure everyone is okay. Call 911 if there are any injuries, damage, or you’re blocking a roadway.
- Make sure you’re somewhere safe (the shoulder of the road or a parking lot).
- Get the following information about all other drivers and vehicles involved:
- License plate
- Make, model, and year of the vehicle (the VIN works, too)
- Insurance information like insurance company and policy number.
- Driver’s license number
- Name
- Phone number
- If there are witnesses, get their contact information.
- Document the damage, if possible.
Take pictures and video.
You should also write down:- What happened/how the damage occurred
- Time of day
- Date
- Weather conditions
- Anything else related to the damage.
- Get a copy of the police report.
- Contact your insurance company or broker (phone number is on your pink card).
Your insurance company or broker will collect information and help you through the next steps. For example, if you have a loss of use coverage, they’ll explain how arranging a rental car or getting repayment for public transit works if your car doesn’t work or needs to go in for repairs.
You’ll be assigned a claims adjuster who investigates and manages the claim. The adjuster will contact you to discuss what happened and keep you updated. The adjuster also negotiates for a settlement, whether your car is being repaired or if it’s a write-off.
A claim is closed when the repairs are complete or payment has been settled.
FAQ’s About Car Insurance in Edmonton
Yes. Every vehicle driven in Edmonton needs at least $200,000 third-party liability, accident benefits and direct compensation for property damage (alberta.ca).
There is no official Edmonton-only figure. The Alberta average was $1,903 in 2025 (IBC), and your own premium depends on your vehicle, record, postal code and coverage.
Read more: 10 Ways to Lower Your Car Insurance Rates in Alberta
No one insurer is cheapest for every Edmonton driver. Each files its own rates, so comparing several through a broker is the fastest way to find the lowest price for your profile.
Generally no. Camera tickets go to the registered owner and carry no demerit points, so they aren’t recorded as driving convictions against your licence.
Likely for basic coverage. The province projects about $366 in savings per vehicle, and approved rates average 13.7% lower for private passenger vehicles, but results vary by driver.
Yes, renew on time so you are never uninsured. Insurers have been told to waive cancellation penalties if you later move to a Care-First policy.
No, Personal items are not covered by your car insurance policy. If stolen, they are covered by the home insurance policy.
Yes, if you carry comprehensive coverage. Items stolen from inside the car are usually claimed on home or tenant insurance.
Only comprehensive coverage pays for hail. Collision on its own does not.
Winter tires aren’t required by Alberta law, but some insurers offer a discount for them. Ask your broker which insurers do.
Yes, in most cases. Alberta insurers must offer mandatory coverage to eligible licensed drivers, and a broker can find insurers that accept higher-risk drivers, though at a higher price.
Start an online quote or call 1-877-218-2008. Have your licence, vehicle details and current policy handy so we can compare like for like.
All car owners in Edmonton are required to have car insurance. Drivers are legally required to carry third-party liability, accident benefits, and direct compensation for property damage auto insurance coverage.
The insurance industry in Alberta follows the all-comers rule, which means you can’t be denied the legal minimum level of car insurance. However, the insurance company can select the rate of your car insurance and deny you optional coverage in case you have a serious traffic conviction or a history of not paying on time.
The all-comers rule is a rule followed by insurance companies operating in Alberta that dictates they have to insure any driver for the legally required minimum level of coverage.
Read more: Do you know all auto insurance coverage?
Grid rating is the metric insurance companies use to determine the car insurance rates for Edmonton drivers based on their driving history.
No, photo radar tickets don’t affect your car insurance rates.
Yes, speeding tickets are a factor that goes into play when determining your car insurance rates in Edmonton. The insurance rates will go up if you get a speeding ticket – Unless it’s a photo radar ticket. The good news is, first tickets may be excused by some insurance companies based on good behaviour.
Your car insurance coverage depends on the insurance options you chose when you set up your policy. Mandatory third-party liability and accidents benefits coverage will help cover damage and medical expenses of other drivers and passengers involved in an accident where you’re at-fault. Mandatory coverage can also cover legal expenses if you’re sued after an accident.
No. Men and women pay similar insurance premiums in Edmonton.
Replacement cost is a loss settlement option where you’ll receive the replacement cost of your vehicle if it’s a write-off after a loss. The replacement cost becomes the price to get the same or very similar car.
Actual cash value is a loss settlement option where you’ll receive the market value or purchase price of your car, minus the depreciation, if it’s a write-off after an accident. It’s the price you’d get if you had sold your auto as-is right before the claim.
Yes, your Edmonton car insurance covers you when travelling south of the border. Make sure to notify your insurance company when driving in the US. Some companies require getting informed when you are in the US or may limit the days you’re covered in the US.
Summary
Car insurance in Edmonton is about to change more than it has in years, so the renewals you sign now and in early 2027 deserve a closer look. Carry liability that protects your savings, keep comprehensive for theft and storms, and know which tickets affect your premium. Sharp Insurance’s licensed brokers compare several insurers for Edmonton drivers and help when you claim.
Get an Edmonton car insurance quote · Call 1-877-218-2008
Sources
To Serve You Best, We Work Hard to Partner with The Best!